Rent or Buy: The Costs Families Don’t See Coming
5 min read | Nation
The monthly payment is the number everyone compares. It’s rarely the one that catches a family off guard.
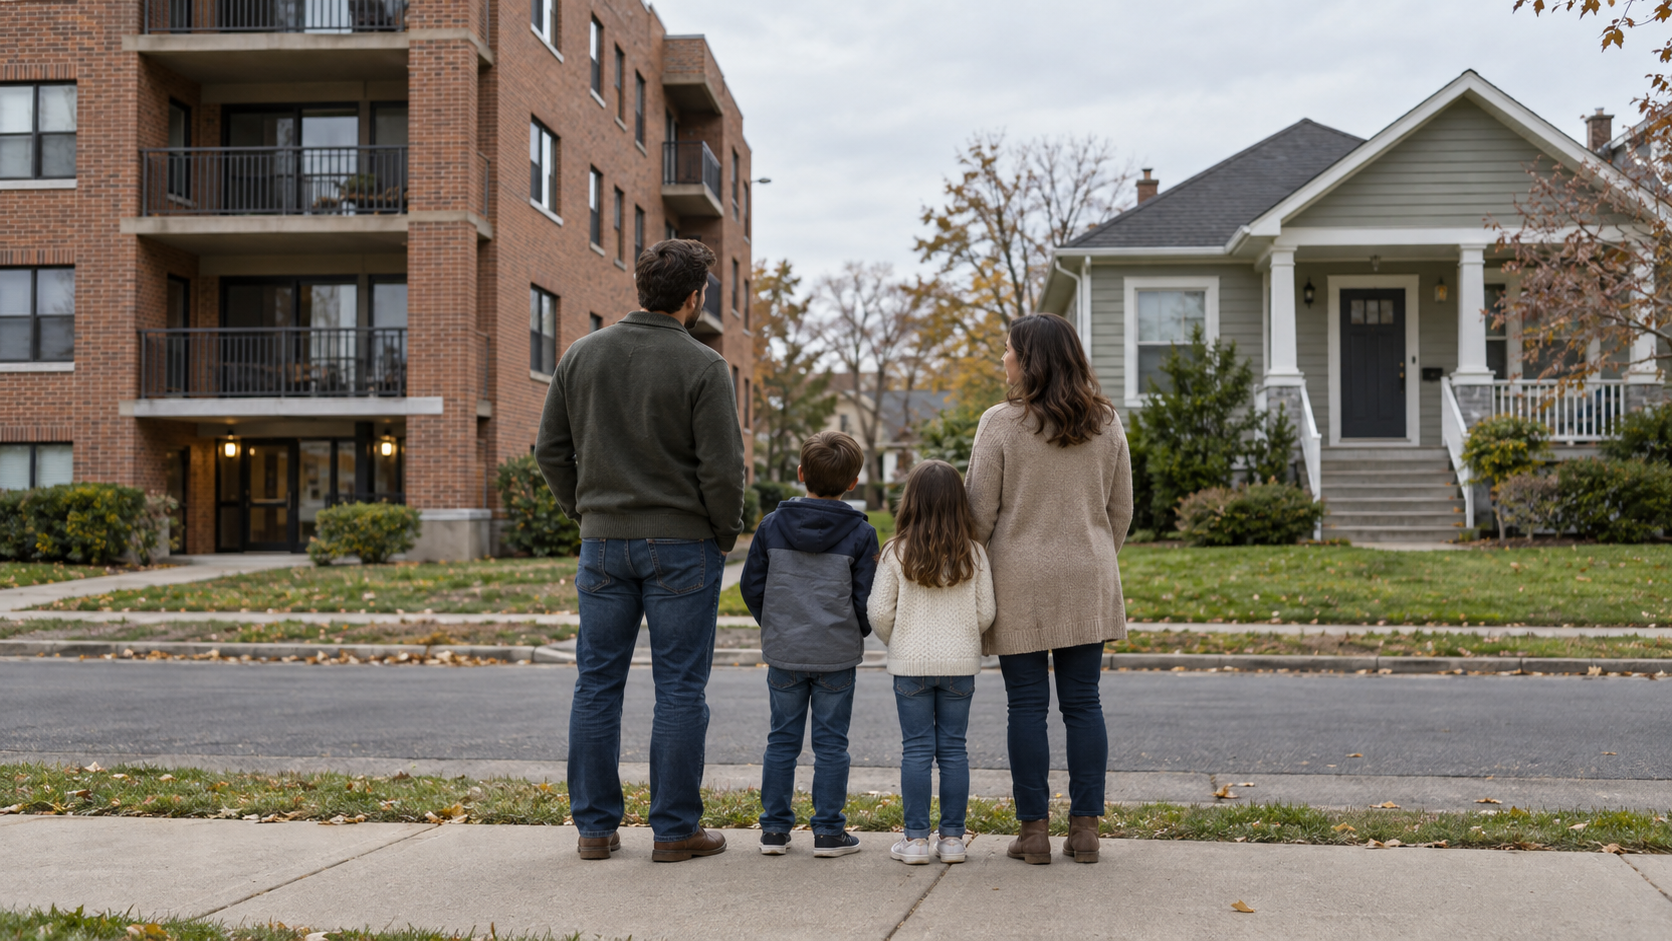
Families deciding between renting and buying usually start with one question: which costs less each month? That’s a fair place to begin. It also leaves out most of the bill. A water heater that quits in January. A rent increase at renewal. A tax reassessment after a purchase. A job offer two states away. Each one lands differently depending on which side of the decision a family is on.
This piece looks at both sides. It doesn’t pick a winner.
What renters pay that the lease doesn’t show
The rent is printed on page one. Plenty of other costs aren’t.
Most leases end. When one does, the landlord can offer a renewal at a higher price, and the family has a few weeks to say yes or start packing. Moving costs real money: a truck or movers, a new deposit, a week of overlapping rent, a day off work. A family that moves every couple of years pays all of it again each time.
Then come the smaller charges. Application fees, pet fees, parking. Renter’s insurance, which some leases require and most families should want anyway, since the landlord’s policy covers the building and not the couch.
And there’s control, which doesn’t show up as a dollar figure until it does. A renter can’t repaint, can’t knock out a wall, and can’t stop an owner from selling the building. After a sale, the new owner might keep the lease, change the terms when it ends, or move in. A child who just settled into a school can end up leaving it over a decision the family had no part in.
What buyers pay that the mortgage doesn’t show
The mortgage payment is the headline. Under it sits a stack of costs that arrive on their own schedule.
Property taxes are usually the first surprise. They’re often folded into the monthly payment, so they feel small, until the local government reassesses the home or changes its rate and the payment moves. Homeowner’s insurance works the same way. An insurer that rethinks the risk in a neighborhood can change the price.
Then repairs. A landlord fixes the roof. An owner is the landlord. A furnace, a sewer line, a cracked slab: none of them give a warning, and none wait for a convenient month. Many owners keep a repair fund for exactly this reason, and families who don’t tend to learn why the hard way.
Closing costs hit before the family has unpacked. Buying takes cash on top of the down payment, for the lender, the title work, the inspection, the appraisal. Some neighborhoods add association dues, which can rise and which often come with rules about the yard, the fence, even the paint color.
And selling has its own price. An owner who has to leave early usually pays agent fees and may not get back what went in. A renter gives notice.
The costs both sides share
Some bills don’t care who holds the title.
Utilities, for one. A drafty older house is expensive to heat whether the family owns it or rents it, and renters often pay the electric and gas bills themselves. Furniture and basic upkeep, for another. And commuting. A cheaper place far from work or school can give back what it saved in gas, car wear, and hours.
Both renters and buyers also pay for the neighborhood in some form: schools, safety, grocery access, distance to grandparents. Those choices push housing prices up or down, and they’re hard to put a number on.
How family life changes the math
Housing decisions rarely stay about housing.
A growing family needs more rooms. A bigger rental costs more each month, and a bigger house takes a bigger loan. School boundaries matter too. Some families buy to land in a particular district. Others rent there for a year first, to find out whether they like it before they commit.
Work pulls on the decision from the other side. A household with a parent who might be transferred, laid off, or offered something better in another city values being able to leave fast. A household with deep roots and steady jobs may value the opposite.
Then there’s time. Plans change. A baby arrives, a parent needs care, a marriage ends, a company closes. The same house can look like a good call one year and a trap the next. A lease can feel like wasted money in one year and like relief in another.
Questions families ask before deciding
No single answer fits every household. A few questions come up again and again:
- How long do we expect to stay in this area?
- What is the full monthly cost, counting taxes, insurance, repairs, and utilities, and not only the payment?
- If a big repair or a rent jump hit in the same year, what could we cover without borrowing?
- How much cash will we have left after the move?
- What would a job change or a new baby do to this plan?
The most useful step is also the plainest. Pull real listings from your own area, one rental and one home for sale, and fill in every line for both. The gaps show up fast on paper.